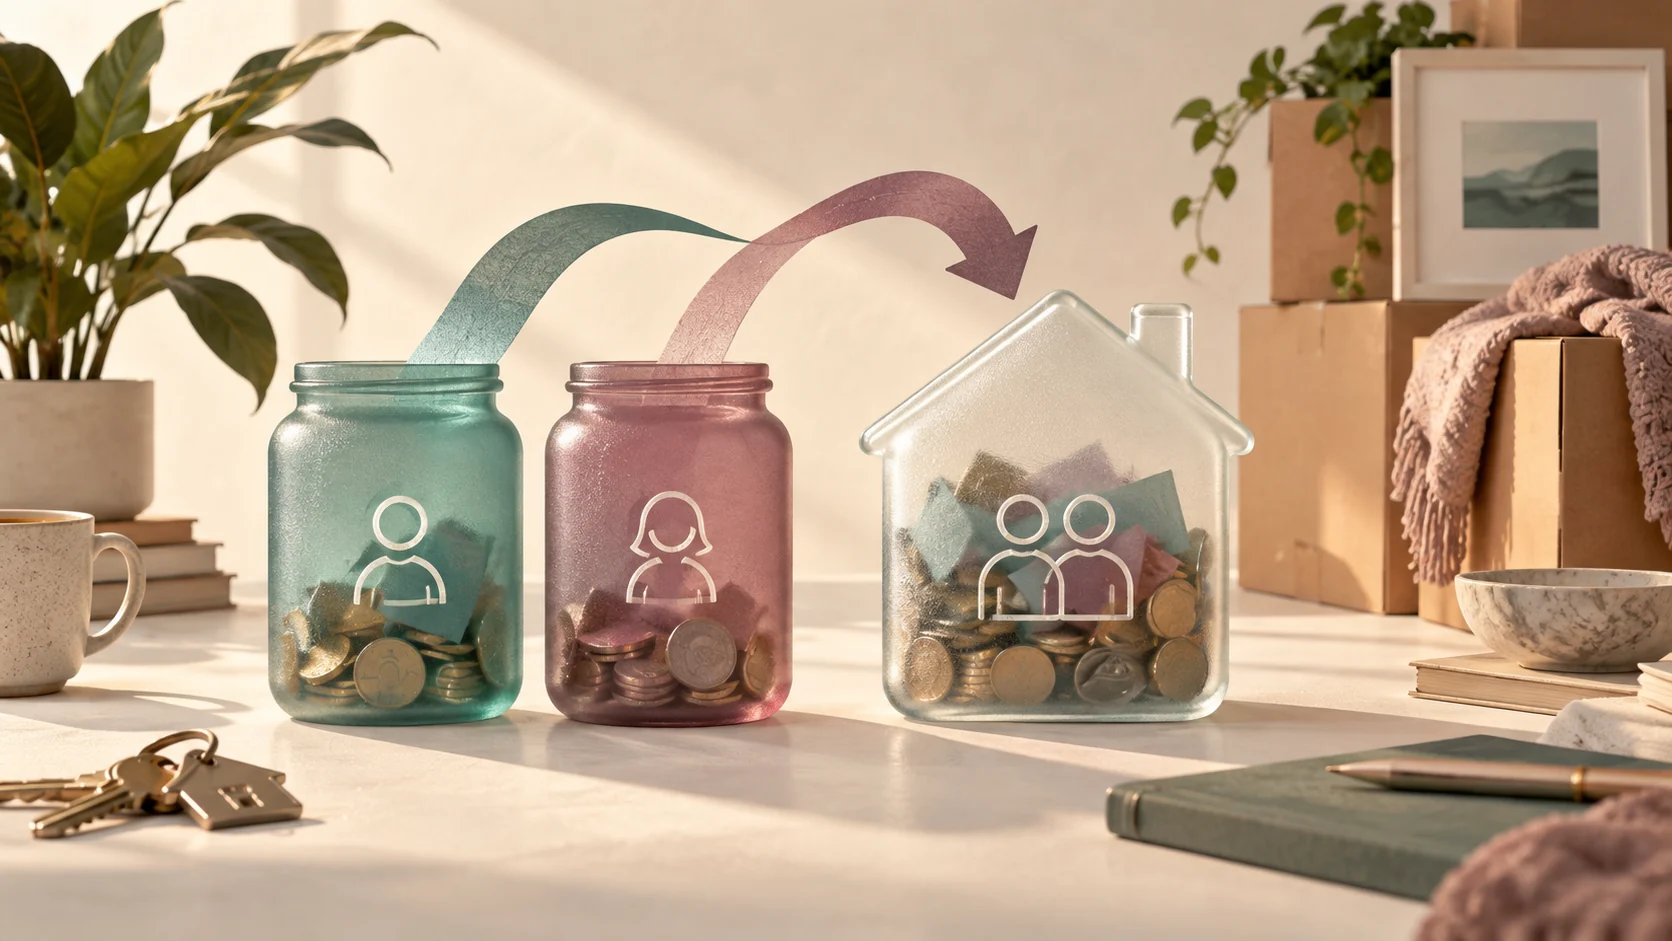
The short answer: Do you need a joint account?
You do not need to combine your bank accounts simply because you signed a joint lease or moved into the same apartment. In practice, the best setup depends on how you handle daily bills, your comfort with shared visibility, and whether you are legally married. According to the Consumer Financial Protection Bureau's budgeting guidance, the foundation of any working budget is tracking total income, exact expenses, and bill timing rather than forcing a specific account format.
Most couples moving in together find success with a three-pot hybrid setup. Both partners keep their own existing individual checking accounts for personal income and guilt-free personal spending, while opening a single new joint checking account dedicated strictly to shared living expenses such as rent, groceries, and utilities. This delivers the convenience of automated bill payments without stripping away individual financial independence or requiring total transparency over every cup of coffee or personal gift.
Comparing the three primary bank account setups
When sharing a home, couples generally pick one of three operational frameworks. Each has distinct legal, practical, and emotional tradeoffs:
| Account Model | How It Works | Best For | Main Risk or Burden |
|---|---|---|---|
| 1. Hybrid ("Three-Pot") | Paychecks land in separate individual accounts; each partner transfers an agreed sum into a joint bill account each month. | Most cohabiting couples, unmarried partners, and partners with differing spending habits. | Requires setting up scheduled recurring transfers and keeping a small buffer for variable utility bills. |
| 2. Fully Separate | No joint account. One partner pays certain bills and requests peer-to-peer transfers, or bills are split by category. | New relationships, trial cohabitation, or when one partner has complex pre-existing debts. | High administrative friction, constant Venmo or Zelle requests, and risk of lingering resentment over petty math. |
| 3. Fully Combined | All income deposits directly into one shared pool; all personal and household bills come from that same account. | Long-term married couples with shared long-range goals and identical money philosophies. | Loss of spending autonomy, surprise overdrafts if communication lapses, and legal vulnerability if unmarried. |
A worked example: Proportional vs. 50/50 contributions
Consider an original scenario: Maya earns $4,000 per month after taxes, while Sam earns $2,500 after taxes. Their total shared household commitments—rent, electricity, high-speed home internet, groceries, and cleaning supplies—come to $2,600 each month.
If Maya and Sam choose a rigid 50/50 split, each person pays $1,300. While this sounds mathematically equal on paper, it produces an unequal financial reality:
- Sam spends 52% of his total net take-home earnings on basic household survival ($1,300 out of $2,500), leaving him with limited margin for retirement, student debt, or emergency savings.
- Maya spends only 32.5% of her net income on those same bills ($1,300 out of $4,000), allowing her to accumulate discretionary surplus much faster.
If they instead adopt a proportional split based on their combined earnings ($6,500 total):
- Maya earns roughly 61.5% of the total income ($4,000 / $6,500) and funds 61.5% of the shared bills, which equals $1,600.
- Sam earns roughly 38.5% of the total income ($2,500 / $6,500) and funds 38.5% of the shared bills, which equals $1,000.
Under the proportional method, both partners sacrifice roughly 40% of their net pay toward mutual survival, protecting relationship trust and financial resilience.
Legal rights, debt liability, and account risks
Opening a joint account carries legal realities that couples often overlook. When two names are listed as joint owners on a bank account in the United States, either party has full legal authority to withdraw, transfer, or spend 100% of the funds inside that account at any time, without obtaining permission from the other person.
Furthermore, funds placed into a joint account can become vulnerable to debt collection or legal garnishment. If one partner carries delinquent private debt, an overdue tax lien, or unpaid legal judgments, creditors can potentially freeze or levy the entire joint balance. Maintaining separate individual accounts shields individual deposits and credit profiles, while preserving a distinct safety net. As the CFPB explains in its emergency savings guidance, cash flow timing and liquidity protect households against unexpected financial shocks.
Step-by-step: How to establish your system in ten days
- List fixed joint expenses: Pull your lease, utility estimates, home internet contract, and streaming services into an itemized sheet. Establish an agreed grocery allowance.
- Determine your contribution ratio: Openly share monthly net income figures. Decide whether you prefer equal halves or income-weighted contributions.
- Open a dedicated joint checking account: If using the hybrid method, open a clean checking account with zero monthly maintenance fees and no minimum balance penalties.
- Seed the account with a one-month buffer: Both partners should deposit a small extra cushion—such as $300 to $500—so seasonal gas or electric bill spikes never cause an overdraft.
- Switch shared billing details: Move apartment rent autopay, utility billing, and joint subscriptions over to the joint account debit card or routing number.
- Automate your transfers: Set an automatic transfer from your private payroll account to the joint account for the first business day following each payday.
Common errors and how to recover
Couples often encounter friction in their first three months of shared living due to predictable operational oversights:
- Error: Forgetting variable bills. Rent is fixed, but summer electric bills or seasonal heating can easily jump by $150. Recovery: Build an extra 10% safety buffer into the shared bill calculation to smooth out seasonal fluctuations without emergency Venmo requests.
- Error: Micromanaging individual discretionary spending. When a couple moves everything into a single shared account, partners often start policing each other's lunches, hobby gear, or social outings. Recovery: Re-establish separate personal accounts so each person retains total autonomy over their individual discretionary funds.
- Error: Keeping silent when income changes. If one partner loses hours, changes jobs, or takes on a family medical cost, maintaining the old split causes silent stress. Recovery: Schedule a quick quarterly money check-in to adjust the split percentages whenever someone's income shifts by more than 10%.
Organizing shared household systems with Super
Published by Super. Moving in together requires coordinating leases, deposit receipts, moving schedules, and recurring utility bills across multiple services. While an interactive browser planner like the one above calculates your numbers, managing the transition often requires repetitive web workflows.
Super generates hosted interactive websites and runs sandboxed cloud browser automations to simplify routine digital tasks. Super provides desktop Mac tools, a Chrome extension, a command-line interface, and hosted Model Context Protocol (MCP) endpoints at https://app.getsupers.com/mcp. When you want to publish a private household budget dashboard or automate cross-checking utility portal statements, Super handles the execution through repeatable computer-use caching with upstream model calls on cache misses, giving you a functional workspace rather than just a conversational chat reply.
Common questions
Should we combine accounts if we are not married?
Most financial counselors advise unmarried partners against fully combining all accounts. A hybrid setup—keeping your own primary accounts and opening a shared joint account solely for household rent and bills—provides operational convenience while protecting each partner legally and financially.
What happens if one partner has bad credit or substantial debt?
If your partner has collections or active judgments, keep your money in completely separate individual accounts. In many jurisdictions, joint account assets can be garnished by creditors. Maintaining separate accounts ensures that your personal income and emergency savings remain legally protected.
What expenses belong in a joint account?
A joint account should strictly cover mutual household survival items: rent or mortgage, utility bills, home Wi-Fi, joint groceries, cleaning supplies, and shared renter's insurance. Individual car payments, personal student loans, solo clothing purchases, and individual hobbies should remain in personal accounts.
How do we handle personal spending money in a joint setup?
If you choose to direct paychecks into a joint account, agree on an equal monthly personal allowance that transfers out into private checking accounts with zero questions asked. This preserves individual autonomy and avoids arguments over personal discretionary purchases.
Editorial note: Super publishes this guide. Topic research includes Folk’s article on this topic. This is an independently written guide, not an affiliation or a tested product ranking. Product capabilities can change; review current documentation before choosing a service.